Driving growth are: inventory depletion in PCs, smartphones, automotive and industrial; electrification in automotive and industrial; AI PCs and AI smartphones and rising memory ASPs.
Wafer capacity pricing is expected to remain flat next year as foundry Lieferanten gradually improve utilisation rates and demand returns from their core fabless customers.
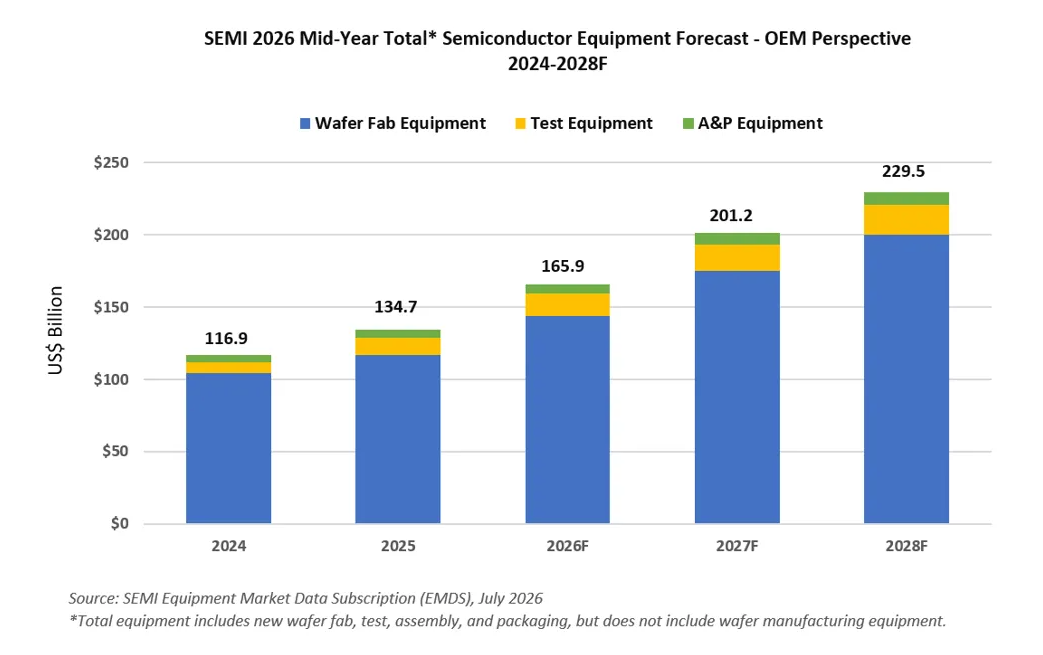
CapEx is expected to improve by 2H24 as Umsatz shipments match end demand and regional ChipAct incentives stimulate investment across the Lieferkette.
By 2026, IDC expects that AI silicon will account for almost $200 billion in semiconductor Umsatzs.”


업계 소식을 최신으로 받아보세요. 저희 뉴스레터를 구독하시면 전문가 팁을 얻을 수 있습니다.