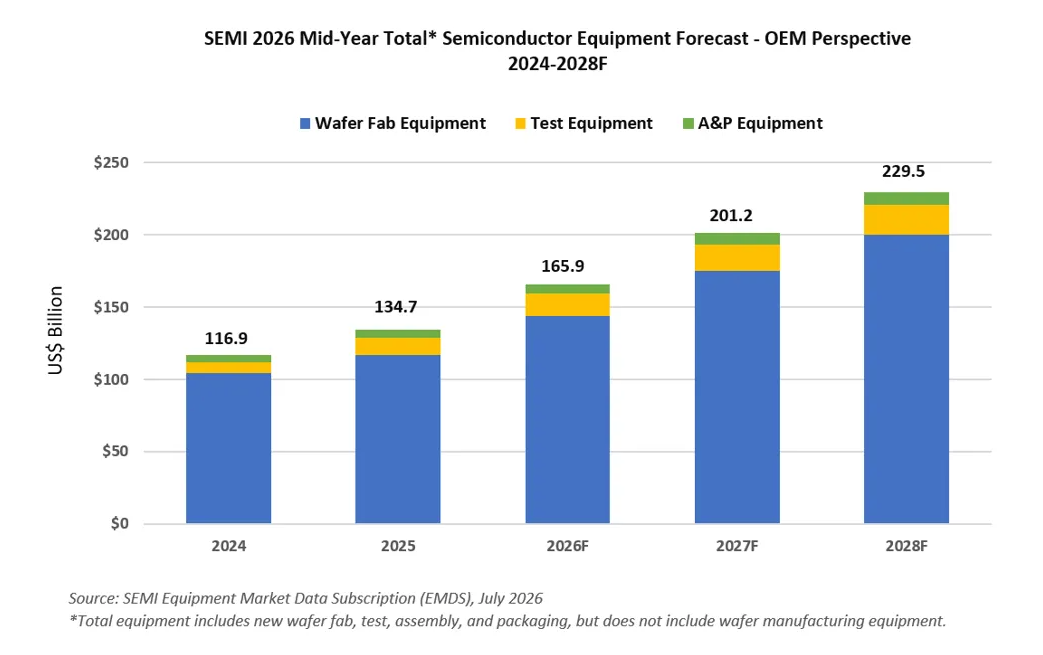
Currently there are bloated inventories for Bauelemente like memory, small case-size ceramic Kondensatoren and automotive MCUs, but FPGAs, analogue ICs, power MOSFETs, MCUs and discretes remain constrained and costly.
In Q3, Lieferzeiten for all elektronische Bauelemente will reduce compared to Q3 2022 with nearly 60% of component Lieferzeiten decreasing versus 1% in Q3 22 with none expected to increase compared to 73% in Q3 22.
Despite inventory reductions that will likely be complete by the end of H1, IC orders, wafer starts, and capacity utilisation will begin to rise and memory pricing will reach its bottom in H2. DRAM prices will start to recover in Q3 and NAND pricing will follow in Q4 or early in 2024.


업계 소식을 최신으로 받아보세요. 저희 뉴스레터를 구독하시면 전문가 팁을 얻을 수 있습니다.